Wednesday, 28 September 2022

Hydrogen Generation Industry ESG Thematic Report, 2022


Hydrogen Generation Industry ESG


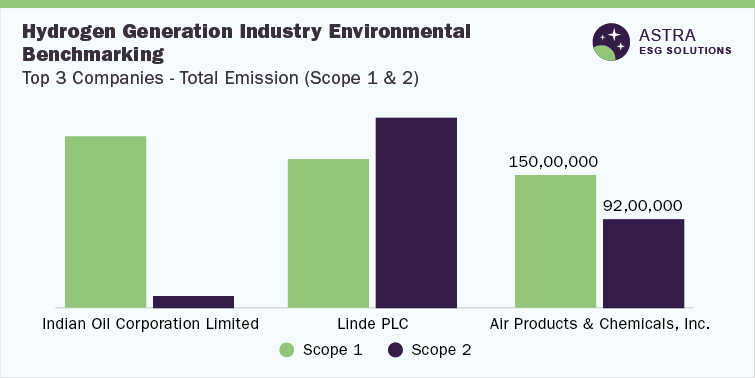
The average ESG disclosure score for the hydrogen generation market stands between 40% and 50%. This conclusion is based on the analysis of more than 60 Environment, Social, & Corporate Governance (ESG) parameters within our ESG scoring framework. Alongside Linde PLC and Indian Oil Corporation, six other market leaders were part of our research. This research identified that only four companies, including Indian Oil Corporation and Linde PLC, scored above the average industry score while the four other leading companies are required to improve their ESG transparency & reporting, as they scored well below 40%. Our research found that majority of the ESG disclosures have been made around the governance metric, with Linde PLC being a leader in this sector when compared to other companies, such as Bloom Energy Corp & Air Liquide, from an overall ESG disclosure point of view.


For More Details: https://astra.grandviewresearch.com/hydrogen-generation-industry-esg-outlook


Environmental insights

Since 1975, there has been a threefold increase in demand for hydrogen. However, its production poses significant consequences for the environment, as it is almost entirely derived from fossil fuels and around 800 million tons of CO2 equivalent emissions are released annually in hydrogen production. The enormity of hydrogen production is such that around 6% of natural gas produced globally goes into producing hydrogen.


Social insights

Within the social component of ESG, improvements around the value chain of a firm, increase in employee engagement & retention, and the method of promoting business continuity are mainly measured. Around seven out of eight companies, i.e., 87.5% of the companies in the industry, have a Human Rights Policy integrated in their supply chain. However, barring some industry leaders, such as Linde PLC and Indian Oil Corporation, none of the other companies have a supplier code of conduct. This outlines opportunities for improvement in terms of value chain operations among other competitors in the industry. Few companies like Bloom Energy Corporation, despite having lower social score, have a publicly available business partner/supply chain policy and furthermore conduct supply chain audits. Similarly, other companies require audits in place to follow due diligence regarding supplier code of conduct.


Governance insights

Financial outperformance is long discussed to have a strong relationship with ESG metrics; however, the governance factor is identified to have a more substantial impact on this factor (financial outperformance), based on empirical evidence. Governance metrics affecting valuation of corporate businesses are corporate governance, code of business conduct, risk & crisis management, tax strategy, supply chain management, and policy influence & materiality.

The industry leaders in social benchmarking are Air Products and Chemicals Inc., with around 80% governance score, followed by Air Liquide, which has a score well above 70%. However, in terms of female representation, Air Liquide has the highest proportion of female on board, at more than 50%, which is higher than the industry leaders Air Products and Chemicals Inc.


Request for Free Demo: https://astra.grandviewresearch.com/hydrogen-generation-industry-esg-outlook/request/rs1


Thursday, 15 September 2022

Solid Oxide Fuel Cell Market To Create Business Opportunities, Based On Increasing Private-Public Partnerships


Solid Oxide Fuel Cell Market


Solid Oxide Fuel Cell Industry Overview


The global solid oxide fuel cell market size is expected to reach USD 7,124.4 million by 2030, registering a CAGR of 40.7% during the forecast period, according to a new report by Grand View Research, Inc. Growing expenditure on infrastructure and industry development is expected to have a positive impact on the global market in the forecast period.


Installers and system providers usually hold stock of significant equipment in the inventory. However, manufacturers face bottlenecks and shortages due to the limited production in countries, severely affected by the COVID-19. Further, upcoming Solid oxide fuel cells (SOFC) based large-scale projects are expected to witness delays in commissioning due to the disruptions in supply chain and halting of on-site construction activities.


Solid Oxide Fuel Cell Market Segmentation

Grand View Research has segmented the global solid oxide fuel cell market based on application and region:


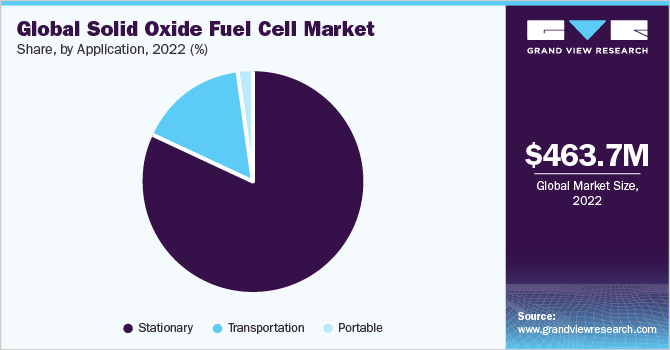
Based on the Application Insights, the market is segmented into Transportation, Portable, Stationary.

  • The stationary application segment led the market and accounted for 81.35% revenue share in 2021. A stationary solid oxide fuel cell system is one of the cleanest and most efficient heat and electricity generation technologies. The performance of these systems is focused on three high-level parameters, including net electrical efficiency, overall efficiency in the case of cogeneration, and durability.
  • European countries such as France and the UK are investing heavily in the R&D of solid oxide fuel cells for power generation and transportation applications. The factors above are expected to boost the growth of the stationary application segment in the SOFC market throughout the forecast period.
  • Collaboration among SOFC vendors and transportation sector vendors is expected to develop SOFC-based systems for transportation applications during the forecast period.
  • For instance, in December 2020, AVL and Ceres signed a strategic collaboration for fuel cell development in order to accelerate product development of SOFC technology across stationary, transportation, and various other applications.
  • With this collaboration, both companies will use a combination of their intellectual property portfolios of solid oxide fuel cell systems to offer new solutions to their clients.


Solid Oxide Fuel Cell Regional Outlook

  • North America
  • Europe
  • Asia Pacific
  • Rest of World


Key Companies Profile & Market Share Insights

In recent years, commercialization of SOFC systems has started with specific niche markets, such as small-scale combined heat and power (CHP) in Japan, and on-site power generations, especially for data centers and military applications in the U.S. Majority of the market participants have focused their research and development activities to develop SOFCs for multiple applications. As a result, the market has witnessed a number of public-private partnerships.


Some prominent players in the global solid oxide fuel cell market include

  • Bloom Energy
  • Mitsubishi Power Ltd.
  • Cummins Inc.
  • Ceres
  • General Electric
  • Fuel Cell Energy Inc.
  • Ningbo SOFCMAN Energy
  • KYOCERA Corporation
  • AVL
  • NGK SPARK PLUG CO., LTD.


Order a free sample PDF of the Solid Oxide Fuel Cell Market Intelligence Study, published by Grand View Research.


About Grand View Research

Grand View Research, U.S.-based market research and consulting company, provides syndicated as well as customized research reports and consulting services. Registered in California and headquartered in San Francisco, the company comprises over 425 analysts and consultants, adding more than 1200 market research reports to its vast database each year. These reports offer in-depth analysis on 46 industries across 25 major countries worldwide. With the help of an interactive market intelligence platform, Grand View Research Helps Fortune 500 companies and renowned academic institutes understand the global and regional business environment and gauge the opportunities that lie ahead.
Wednesday, 14 September 2022

Organic Rankine Cycle Market To Predict Global Expansion, Due To Rise In The Adoption Of Renewable Energy


Organic Rankine Cycle Market


Organic Rankine Cycle Industry Overview


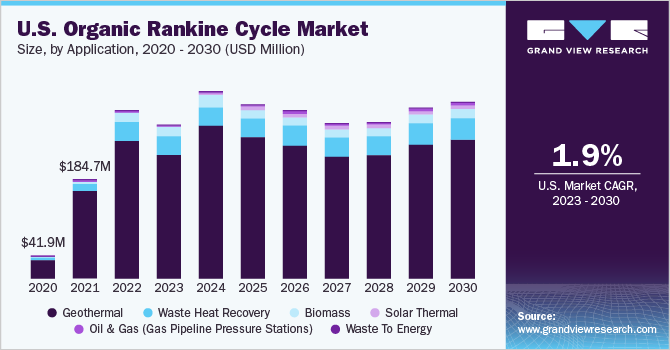
The global organic rankine cycle market size is expected to reach USD 1.07 billion by 2030, according to a new report by Grand View Research, Inc. The market is expected to expand at a CAGR of 3.3% from 2022 to 2030. A rise in the adoption of renewable energy in countries such as the U.S., China, Germany, and Canada is making supporting regulations and providing financial incentives for the deployment of renewable energy. Financial incentives such as feed-in-tariff, subsidies, and tax benefits are some of the major tools utilized by countries around the world to attract investment in the renewable energy sector. These factors propel the growth of the organic rankine cycle (ORC) market in the near future.


The supply chains of spare parts for ORC systems are majorly affected due to the shutdown of production facilities of the manufacturers. The manufacturing of most components in the energy & power sector is slowing down considerably. In addition, local and international travel restrictions, quarantine requirements, and lockdowns have caused delays in shipments of already manufactured parts to be supplied to the distributors and end-users. ORC manufacturers usually have access to an adequate supply of critical parts, devices, components, and materials for emergencies.


Organic Rankine Cycle Market Segmentation

Grand View Research has segmented the global Organic Rankine Cycle (ORC) market based on application and region:


Based on the Application Insights, the market is segmented into Waste Heat Recovery, Biomass, Geothermal, Solar Thermal, Oil & Gas (Gas pipeline pressure stations), Waste to Energy.

  • The geothermal segment led the market and accounted for the largest revenue share of 61.71% in 2021.
  • The major reason for the dominance of the geothermal segment is due to the large-scale megawatt capacity of these geothermal projects as compared to other application segments such as biomass, waste heat recovery, and solar thermal.
  • Countries with high geothermal potential such as the U.S., Turkey, Kenya, New Zealand, and Indonesia have taken significant steps to utilize the available geothermal potential available in their respective countries. For instance, from 2017 to 2018 Indonesia started the commercial operation of geothermal power plants with a cumulative capacity of 330 MW.


Organic Rankine Cycle Regional Outlook

  • North America
  • Europe
  • Asia Pacific
  • Central & South America
  • Middle East & Africa (MEA)


Key Companies Profile & Market Share Insights

The key players operating in the market are Ormat, Turboden, and Exergy, along with a few medium and small regional players. Leading market players compete based on their product development capabilities and new technologies used in product formulations.


Some prominent players in the global organic rankine cycle market include

  • Elvosolar, a.s
  • Enogia SAS
  • Exergy S.p.A.
  • General Electric
  • INTEC GMK
  • Ormat
  • TAS
  • Triogen
  • Turboden S.p.A.
  • Zhejiang Kaishan Compressor Co., Ltd.


Order a free sample PDF of the Organic Rankine Cycle Market Intelligence Study, published by Grand View Research.


About Grand View Research

Grand View Research, U.S.-based market research and consulting company, provides syndicated as well as customized research reports and consulting services. Registered in California and headquartered in San Francisco, the company comprises over 425 analysts and consultants, adding more than 1200 market research reports to its vast database each year. These reports offer in-depth analysis on 46 industries across 25 major countries worldwide. With the help of an interactive market intelligence platform, Grand View Research Helps Fortune 500 companies and renowned academic institutes understand the global and regional business environment and gauge the opportunities that lie ahead.
 

Friday, 12 August 2022

Gas Turbine Services Market Is Developing Rapidly, Based On Growing Population And Rapid Urbanization Till 2027


Gas Turbine Services Industry Overview


The global gas turbine services market size is expected to reach USD 55.1 billion by 2027, according to a new report by Grand View Research, Inc., registering a CAGR of 9.8% over the forecast period. The increasing adoption of gas turbines on account of their ability to produce low exhaust gas pollution is expected to drive market growth. These systems are increasingly being used owing to their tremendous energy-producing capacity and multiple fuel capability. They also have the capacity to operate continuously at baseload for numerous hours. Furthermore, low operational cost and high efficiency and durability offered by these systems is expected to drive gas turbine service market growth.


Gas Turbine Services Market Segmentation

Grand View Research has segmented the global gas turbine services market on the basis of turbine type, turbine capacity, service type, service provider, end-use, and region:


Based on the Turbine Type Insights, the market is segmented into heavy duty, industrial, aeroderivative.

  • Heavy duty turbines emerged as the largest segment, which accounted for a share of over 52.0% in the global market. It is also projected to witness the fastest growth rate over the forecast period.
  • The growth of the segment is mainly attributed to the wide application scope of these turbines in chemical plants, refineries, and power utilities.
  • Furthermore, heavy-duty turbines provide improved thermodynamic cycles and an optimized production process.
  • Advancements in technology have also enhanced the power output, efficiency, and environmental compatibility of these turbines. These factors are projected to drive the demand for heavy-duty turbine services over the forecast period.
  • Industrial turbines accounted for a share of more than 38.0% in 2019 and are projected to register the second-highest CAGR over the forecast period.
  • Positive trends regarding the development of key manufacturing sectors across the globe are supporting the growth potential for industrial gas turbine services. This is due to the development of both heavy and light industries, which is projected to increase the need for services for gas turbines.
  • Moreover, the growing population and rapid urbanization are creating an increased demand for electricity, which in turn drives the demand for industrial gas turbines and the subsequent need for services for these systems.


Based on the Turbine Capacity Insights, the market is segmented into <100 mw, 100 to 200 mw, >200 mw.

  • The >200 MW segment emerged as the largest segment with a share of over 39.0% in 2019. The development of the power generation sector along with an increased focus on generating electricity through sustainable energy resources is the major growth driver for this segment. 
  • Growing urbanization has a significant impact on the development of the building and cement industries. The projected growth of these end-use industries is estimated to drive the demand for large and heavy-duty turbines. 
  • The 100 to 200 MW segment accounted for the second-largest share in 2019. This is primarily attributed to the growth of end-use industries such as sugar mills, pharmaceuticals, oil and gas, plastic and resin manufacturing, glass manufacturing, and intermediate chemicals.
  • The growth of the <100 MW segment is primarily driven by the rise in aerospace activities and the increasing application scope of turbines in the oil and gas sector.
  • The smaller size of <100 MW turbines make them an ideal product for offshore locations where the power-to-weight ratio is an important parameter while determining which turbine unit would be the most suitable option.


Based on the Service Type Insights, the market is segmented into maintenance & repair, overhaul, spare parts supply.

  • Spare parts supply emerged as the largest service type segment, which accounted for a share of more than 63.0% of the global gas turbine services market in 2019.
  • The components of the gas turbine have a specific lifespan after which they require periodic replacement, thereby driving the growth of the segment.
  • Maintenance and repair activities are performed regularly in developed regions such as Europe and North America.
  • The rise in awareness regarding the benefits of periodic maintenance and development in data collection technologies are expected to drive the growth of this segment over the forecast period.
  • An overhaul is projected to be the second-fastest-growing segment in the global market from 2020 to 2027. Overhaul comprises the inspection, repair, replacement, and disassembly of subcomponents.
  • A gas turbine operates under harsh operating conditions which include corrosion, temperature, and stress. The power turbine and generator of the unit are exposed to high-temperature gases, along with vibration and thermal cycling which produce mechanical and thermal stress in turbine components.
  • Exposure to combustion gases results in the corrosion of the power turbine and gas generator units and therefore requires replacing after a certain interval. These factors are expected to drive the need for overhaul services over the forecast period.


Based on the Service Provider Insights, the market is segmented into oem, non-oem.

  • OEM dominated the service provider segment of the market in 2019. This dominance is mainly attributed to factors such as technological capability, wide geographical presence, skilled workforce, and brand value of original equipment manufacturers (OEMs).
  • OEMs have well-established R&D infrastructure as well as data management centers that enable them to observe the unit from remote locations to determine the accurate real-time health of the unit. OEMs also offer multiyear service agreements to buyers which cover a range of services.
  • OEMs generally offer multiyear agreements to buyers during new gas turbine installations. Most buyers prefer OEMs owing to their technological and service capabilities and opt for multiyear agreements, further enabling OEMs to consolidate their market position.
  • Furthermore, OEMs are aggressively expanding their presence by acquiring small-scale companies.
  • Non-OEMs service providers accounted for a market share of about 39.0% in 2019. They have a presence in price-sensitive markets such as India, China, and Thailand as consumers in emerging countries are shifting from OEMs to independent service providers to cut operational costs.


Based on the End-use Insights, the market is segmented into power generation, oil & gas, other industrial.

  • Power generation emerged as the largest end-use segment in the global market with a share of over 62.0% in 2019. The increasing need for electricity drives the demand for gas turbines in the power generation sector.
  • Key competitors are still skeptical regarding the demand for gas turbines in the power generation segment. Volatility in the prices of natural gas acts as a restraint for the growth of the market in this segment.
  • Factors such as growing population, rise in industrial activities, and increasing vehicle ownership ratio are leading to high demand for oil production.
  • This is projected to increase the application of gas turbines in the oil and gas industry, which faced a major challenge in the past owing to the drop in oil prices.


Gas Turbine Services Regional Outlook

  • North America
  • Europe
  • Asia Pacific
  • Commonwealth of Independent States
  • Central & South America
  • Middle East & Africa (MEA)


Key Companies Profile & Market Share Insights

The key players adopt strategies such as providing multiyear services contracts to existing and new power plant owners to further enhance their market position. Competition among key vendors is based on the performance and efficiency of their manufactured gas turbines as well as associated services provided by them to their customers.


Some prominent players in the global gas turbine services market include

  • General Electric
  • Siemens AG
  • Mitsubishi Hitachi Power Systems, Ltd. (MHPS)
  • MAN Energy Solutions
  • Kawasaki Heavy Industries, Ltd.
  • Ansaldo Energia S.p.A.


Order a free sample PDF of the Gas Turbine Services Market Intelligence Study, published by Grand View Research.


About Grand View Research

Grand View Research, U.S.-based market research and consulting company, provides syndicated as well as customized research reports and consulting services. Registered in California and headquartered in San Francisco, the company comprises over 425 analysts and consultants, adding more than 1200 market research reports to its vast database each year. These reports offer in-depth analysis on 46 industries across 25 major countries worldwide. With the help of an interactive market intelligence platform, Grand View Research Helps Fortune 500 companies and renowned academic institutes understand the global and regional business environment and gauge the opportunities that lie ahead.
Tuesday, 26 July 2022

Flywheel Energy Storage System Market To Predict Global Expansion, Due To Increasing Demand From UPS And Data Center Application


Flywheel Energy Storage System Industry Overview


The global flywheel energy storage system market size is expected to reach USD 737.99 million, registering a CAGR of 9.8% during the forecast period from 2022 to 2030, according to a new report by Grand View Research, Inc. The rise in climate change issues and environmental concerns led various countries, around the world, to reduce their carbon footprint for power generation and transportation sector and to opt for cleaner and green energy technologies owing to the demand for flywheel energy storage is growing in its specific application segments.


The data center is the highest penetration application segment in the flywheel energy storage market due to the growing demand for energy storage devices, in order to overcome the risk of interruptions at the main power supply. UPS, with the second-highest penetration, is one of the most important application areas of flywheel energy storage systems. The growing demand for uninterrupted power supply from industries across various sectors is driving the market for UPS.


Flywheel Energy Storage System Market Segmentation

Grand View Research has segmented the global Flywheel Energy Storage System Market report based on application and region:

Based on the Application Insights, the market is segmented into UPS, data center, distributed energy generation, transport and others

  • The others segment led the market and accounted for 44.74% share of the global revenue in 2021. Frequency regulation applications of flywheels are included in this segment. These applications are gaining importance due to the growing demand for uninterrupted power from commercial workstations and factories.
  • Uninterruptible power supply (UPS) is one of the major application areas of flywheel energy storage systems. Power failures can cause huge losses in businesses and commercial workstations.
  • Flywheel UPS systems can be used to overcome the problems faced by sudden dips or glitches in electric and voltage supplies. Also, since this technology does not involve the use of fossil fuels, it is environmentally friendly.
  • Flywheels are used as intermediate energy storage systems for transport applications such as automobiles.
  • Flywheel storage energy systems are more commonly used in Formula 1 cars and hybrid vehicles. However, manufacturers such as Maruti Suzuki have adopted this technology for passenger vehicles also.
  • Distributed energy generation involves the generation of power at the place of consumption. This method has several advantages such as elimination of cost, inefficiencies, and complexities related to power generation as compared to centrally generated power.
  • Distributed energy generation aids to provide faster power backup in case of natural disasters such as floods and earthquakes. This has been one of the major drivers for the deployment of distributed energy generation sources in areas, which are prone to natural disasters.


Flywheel Energy Storage System Regional Outlook

  • North America
  • Europe
  • Asia Pacific
  • Central and South America
  • Middle East & Africa (MEA)


Key Companies Profile & Market Share Insights

Industry players are practicing several growth policies such as strategic partnerships with other local market players, to set up flywheel energy storage systems across various countries. Such policies enable companies to improve their foothold in the global market. Some of the major manufacturers are exploring other markets and expanding their presence in emerging economies. Thus the companies are keenly looking at certain ways to grow their existence in untapped countries to enhance their market share.

Some of the prominent players in the global flywheel energy storage system market include:

  • Langley Holdings plc
  • Amber Kinetics, Inc.
  • Stornetic GmbH
  • POWERTHRU
  • Energiestro
  • VYCON, Inc.
  • Bc New Energy (Tianjin) Co., Ltd. (BNE)
  • Beacon Power, LLC
  • PUNCH Flybrid
  • Kinetic Traction Systems, Inc.


Order a free sample PDF of the Flywheel Energy Storage System Market Intelligence Study, published by Grand View Research.

Liquefied Natural Gas Market Expected To Reach $208.85 billion By 2030, Based On Growing Focus On Projects Related To Distributed Power & Utility


Liquefied Natural Gas Industry Overview


The global liquefied natural gas market size is expected to reach USD 208.85 billion by 2030, according to a new report by Grand View Research, Inc. The market is expected to expand at a CAGR of 8.1% from 2022 to 2030. The growing demand for electric power through clean energy sources is likely to propel the market growth over the coming years. A growing focus on projects related to distributed power & utility is anticipated to bolster the market growth over the next eight years. The projected growth in natural gas in the power generation business is also likely to create more demand for liquefied natural gas (LNG) across various countries.


Liquefied Natural Gas Market Segmentation

Grand View Research has segmented the global liquefied natural gas market report based on application and region:


Based on the Application Insights, the market is segmented into transportation fuel, power generation and others


  • The power generation application segment accounted for the largest value share of 47.44% in 2021. Growing demand for natural gas also helps in reducing the emission of harmful greenhouse gas emissions.
  • Increased usage of this fuel in the mining, industrial and power generation sectors has displayed a significant change over the historic period.
  • A decline in the prices, as well as low fuel switching costs, are enhancing the industry growth in the transportation and power generation application.
  • Owing to the benefits associated with LNG coupled with the upsurge in the production of rich natural gas in the Northern American region and others have directed sharp attention towards natural gas to be used as a green transportation fuel.
  • Diesel and petrol have been the default options for vehicle fuels. However, there has been a shift from traditional fuel to available better choices on the market such as natural gas that give the same performance in terms of power, acceleration, and cruising speed, but with added financial and environmental benefits.
  • LNG is typically less expensive than diesel giving lower running costs over the medium to long distances and the lowest total cost of ownership compared to conventional fuels. It also has strong environmental benefits that improve air quality by reducing greenhouse gas emissions.


Liquefied Natural Gas Regional Outlook

  • North America
  • Europe
  • Asia Pacific
  • Central & South America
  • Middle East & Africa (MEA)


Key Companies Profile & Market Share Insights

The market is characterized by the presence of several key players and a few media and small-scale regional players. Many of the companies have their sector that they focus on and have a very high penetration in that sector. Virtual pipeline systems deliver liquefied natural gas by road, rail, and waterways to areas not connected by physical pipelines.

Some of the prominent players operating in the global liquefied natural gas market are:

  • British Petroleum (BP) p.l.c.
  • Chevron Corporation
  • China Petroleum & Chemical Corporation
  • Eni SpA
  • Equinor ASA
  • Exxon Mobil Corporation
  • Gazprom Energy
  • PetroChina Company Limited
  • Royal Dutch Shell PLC
  • Total S.A.


Market Industry Development

  • February 2020: ExxonMobil India LNG Limited has signed a Letter of Cooperation with Indian Oil Corporation Limited and Chart Industries, Inc. to establish a system of transportation infrastructure to expand gas access in India. s


Order a free sample PDF of the Liquefied Natural Gas Market Intelligence Study, published by Grand View Research.


About Grand View Research

Grand View Research, U.S.-based market research and consulting company, provides syndicated as well as customized research reports and consulting services. Registered in California and headquartered in San Francisco, the company comprises over 425 analysts and consultants, adding more than 1200 market research reports to its vast database each year. These reports offer in-depth analysis on 46 industries across 25 major countries worldwide. With the help of an interactive market intelligence platform, Grand View Research Helps Fortune 500 companies and renowned academic institutes understand the global and regional business environment and gauge the opportunities that lie ahead.

Wednesday, 20 July 2022

Battery Market To Create Business Opportunities, Owing To High Demand For Portable Electronics


Battery Industry Overview


The global battery market size is expected to reach USD 310.8 billion by 2027, according to a new report by Grand View Research, Inc., expanding at a CAGR of 14.1% from 2020 to 2027. Technological advancements in terms of enhanced efficiency and cost reduction are likely to open new paths for the global market over the estimated period. Increasing use in aircraft emergency systems in case of non-availability of auxiliary power units (APUs) for ground operations, restarting, and braking the auxiliary power units is expected to propel high capacity battery demand. High density and low cost of the lead-acid battery will support use in grid storage and emergency power supply applications, thus augmenting the market growth.


Battery Market Segmentation

Grand View Research has segmented the global battery market report on the basis of product, application, and region:


Based on the Product Insights, the market is segmented into lead acid, lithium ion, nickel metal hydride, nickel cadmium and others

  • The lead-acid battery segment accounted for the largest share of 29.5% in 2019 on account of expanding applications in uninterrupted power supply (UPS), automotive, telecommunication, transport vehicles, and electric bikes.
  • High use of uninterrupted power supply devices in the oil and gas, healthcare, and chemical sectors for constant power supply will drive demand for a lead-acid battery. These batteries are used in critical applications on account of their high reliability and low cost.
  • The lithium-ion product segment was valued at USD 31.8 billion in 2019 owing to its growing demand for electric vehicles (EVs) and grid storage as it offers high-energy density solutions and is lightweight.
  • Li-ion batteries are expected to capture a substantial portion in the market over the projected period on account of their low energy density and high lead content.
  • Lithium-ion batteries are expected to infiltrate lead-acid battery applications, such as storage and automobiles, plug-in electric vehicles, and electric vehicles, thus holding a majority market share by 2027.
  • The adoption of Li-ion batteries in electric vehicles, energy storage systems, and portable devices is expected to rise at a fast pace owing to their low maintenance properties and higher energy densities.
  • Nickel-cadmium and nickel-metal hydride batteries are the next major segments of the global market.


Based on the Application Insights, the market is segmented into automotive batteries, industrial batteries and portable batteries

  • The automotive application segment led the market and accounted for a 34.3% share of the total revenue in 2019 on account of increasing demand for EVs, plug-in hybrid vehicles, and HEVs.
  • Starting, lighting, and ignition (SLI) application in the automotive sector has contributed to high battery demand for SLI in vehicles. Industrial applications include forklifts with extra material handling equipment, telecom, energy storage, UPS, emergency lighting, security, road signs, medical, and control and switchgear.
  • High demand for consumer electronics is likely to drive the portable application segment. This segment is expected to observe substantial growth in terms of consignments, though, with low revenues and small size, it does not subsidize a major share in the market.
  • Batteries are mainly used in various industrial applications such as off-grid and grid energy storage systems, UPS, power backup, machinery and marine equipment, industrial automation systems, agricultural machinery, defense and aviation, electronics, oil and gas, and civil infrastructure.
  • An increase in the usage of electric-powered forklifts and automation systems in industrial logistics and storage warehouses, workshops, large-scale facilities, and factories is expected to drive the consumption of industrial batteries during the estimated period.


Battery Regional Outlook

  • North America
  • Europe
  • Asia Pacific
  • Central and South America
  • Middle East & Africa (MEA)


Key Companies Profile & Market Share Insights

The global market is characterized by intense competition due to the presence of major companies across the region. The market is categorized with forwarding integration, where key battery producers are also indulged in the usage and distribution of such batteries. Key participants depend on strategies such as JVs and M&A to strengthen their presence in the market. They also focus on increasing their market productivity and share through R&D activities and product innovations. 

Some of the prominent players in the battery market include:

  • GS Yuasa International Ltd.
  • BYD Company Ltd.
  • A123 Systems LLC
  • Hitachi Chemical Co., Ltd.
  • Johnson Controls
  • NEC Corporation,
  • Panasonic Corporation
  • Samsung SDI Co., Ltd.
  • Toshiba Corporation
  • LG Chem Ltd.
  • Saft
  • Sony Corporation
  • Eveready Industries
  • Contemporary Amperex Technology Co.


Order a free sample PDF of the Battery Market Intelligence Study, published by Grand View Research.