Tuesday, 10 September 2024

Innovations In The Fuel Cell Market: Technologies Shaping The Future


Fuel Cell Industry Overview


The global fuel cell market size was estimated at USD 7.35 billion in 2023 and is expected to grow at a compound annual growth rate (CAGR) of 27.1% from 2024 to 2030. Increasing demand for unconventional energy sources is one of the key factors driving the growth. Growing private-public partnerships and reduced environmental impact are expected to propel the demand. Governments across the globe are anticipated to supplement the developments by offering support in different forms, including funding R&D activities and funding suitable financing programs. Building a robust regulatory framework is vital as government enterprises need to provide an environment that is favorable for investment.


Gather more insights about the market drivers, restrains and growth of the Fuel Cell Market


Most of the U.S. states, such as California and New York, have set mandates to limit the carbon emissions from commercial and industrial end users in the country. This has resulted in end users opting for clean energy technologies to comply with the mandate and limit their carbon footprint. Bloom Energy, one of the major fuel cell vendors in the U.S., provides its bloom energy servers for power generation application to aid commercial and industrial end users limit their carbon footprint.


For instance, in September 2023, FuelCell Energy, Inc. and Toyota Motor North America announced the completion of Tri-gen system at Toyota's Port of Long Beach operations. Tri-gen is an example of FuelCell Energy's ability to scale hydrogen-powered fuel cell technology. Such innovative ideas is expected to foster the demand of fuel cell market over forecast period.


Fuel cell market is a rapidly growing sector with a wide range of potential opportunities. The technology is constantly improving, with new materials and designs leading to increased efficiency and performance. This is making fuel cells more attractive for a wider range of applications. Transportation sector is one of the largest markets for fuel cells. Fuel cell electric vehicle (FCEVs) offer several advantages over battery-electric vehicles (BEVs), such as longer range and faster refueling times. As the cost of FCEVs comes down and the hydrogen infrastructure grows, the market for fuel cell vehicles is expected to boom. Companies operating in the market continuously launch new products in order to pace up with the growing fuel cell technology. For instance, in January 2024, Nikola Corporation launched 42 and wholesaled 35 Class 8 Nikola hydrogen-powered fuel cell electric vehicles (FCEVs) under HYLA brand for U.S. and Canada customers. The trucks are featured to run with a range of 500 miles with an estimated fueling time as low as 20 minutes.


Browse through Grand View Research's Power Generation & Storage Industry Research Reports.


• The global battery market size was estimated at USD 118.20 billion in 2023 and is projected to grow at a CAGR of 16.1% from 2024 to 2030. The market is experiencing rapid growth, driven primarily by the increasing adoption of electric vehicles (EVs) and the expansion of renewable energy infrastructure.


• The global refrigerant market size was estimated at USD 14.26 billion in 2023 and is projected to grow at a CAGR of 4.7% from 2024 to 2030.The industry is experiencing growth due to increased demand from various end-use sectors, particularly the commercial & industrial refrigeration industry.


Fuel Cell Market Segmentation


Grand View Research has segmented the global fuel cell market report based on product, components, fuel, size, application, and end-use, and region:


Fuel Cell Product Outlook (Volume, Units; Capacity, MW, Revenue, USD Million, 2018 - 2030)
• PEMFC
• PAFC
• SOFC
• MCFC
• AFC
• Others


Fuel Cell Components Outlook (Volume, Units; Capacity, MW, Revenue, USD Million, 2018 - 2030)
• Stack
• Balance of Plant


Fuel Cell Fuel Outlook (Volume, Units; Capacity, MW, Revenue, USD Million, 2018 - 2030)
• Hydrogen
• Ammonia
• Methanol
• Ethanol
• Hydrocarbon


Fuel Cell Size Outlook (Volume, Units; Capacity, MW, Revenue, USD Million, 2018 - 2030)
• Small-scale
• Large-scale


Fuel Cell Application Outlook (Volume, Units; Capacity, MW, Revenue, USD Million, 2018 - 2030)
• Stationary
• Transportation
• Portable


Fuel Cell End-use Outlook (Volume, Units; Capacity, MW, Revenue, USD Million, 2018 - 2030)
• Residential
• Commercial & Industrial
• Transportation
• Data Centers
• Military & Defense
• Utilities & Government


Fuel Cell Regional Outlook (Volume, Units; Capacity, MW, Revenue, USD Million, 2018 - 2030)
• North America
o U.S.
o Canada
o Mexico
• Europe
o Germany
o France
o U.K.
o Italy
o Spain
• Asia Pacific
o China
o Japan
o South Korea
o India
o Taiwan
o Australia
• Central & South America
o Brazil
o Argentina
• Middle East & Africa
o Saudi Arabia
o UAE
o South Africa


Order a free sample PDF of the Fuel Cell Market Intelligence Study, published by Grand View Research.


Key Companies profiled:
• Ballard Power Systems
• Bloom Energy
• Ceres Power Holdings PLC
• Doosan Fuel Cell America, Inc.
• FuelCell Energy, Inc.
• Hydrogenics Corporation
• Nedstack Fuel Cell Technology B.V.
• Nuvera Fuel Cells LLC
• Plug Power, Inc.
• SFC Energy AG


Key Fuel Cell Company Insights


• In November 2023, Honda in association with General Motors displayed a prototype of its next-generation hydrogen fuel cell system at European Hydrogen Week in Brussels. The company is planning to expand its portfolio in fuel cell technology.


• In December 2023, General Motors and Komatsu announced to develop a hydrogen fuel cell power module for the Japanese construction machinery maker's 930E electric drive mining truck.


• In January 2023, Cochin Shipyard Limited initiated research activities for the development of a hydrogen-fueled electric vessel based on low-temperature proton exchange membrane technology.


• In January 2023, Advent Technologies collaborated with Alfa laval to explore the application of high-temperature proton exchange membrane fuel cells in marine applications.

Sunday, 8 September 2024

Diesel Generator Market Segmentation And Applications Across Various Industries

 Diesel Generator Industry Overview


The global diesel generator market size was estimated at USD 16.36 billion in 2023 and is expected to grow at a CAGR of 9.6% from 2024 to 2030. Increasing energy demand globally far outstrips the supply. Factors, such as continuous population growth, infrastructure development, and rapid industrialization in emerging economies drive power demand.


Diesel generators are favoured for their numerous benefits, including low operating costs and superior fuel efficiency, making them particularly popular in developing areas, notably the Asia Pacific region. Despite these advantages, they also have several disadvantages, such as noise pollution and the emission of harmful gases. The World Nuclear Association has predicted that the electricity demand is likely to double from current levels. In addition, the U.S. Department of Energy forecasts that solar energy will become the most plentiful energy source available.


Gather more insights about the market drivers, restrains and growth of the Diesel Generator Market


Significant growth in the economies of major developing nations, such as India and Brazil, is expected by 2050. India is expected to grow from being the third largest to the second largest economy in the world, only after China in terms of GDP at PPP (purchase power parity). Countries, such as Brazil, India, and South Africa, are already suffering due to a low power supply. Emerging economies are expected to account for 65% of the global economy. The U.S. market is anticipated to witness substantial growth owing to rising costs of power outages across several IT-enabled service firms and data centers and growing consumer awareness of the need for a reliable emergency power supply. In addition, the market is also driven by the rising vulnerability of grid power stations to disasters caused by changing weather conditions across the region.


Solution providers are mainly responsible for manufacturing, installing, maintaining, and repairing generator systems. Dealers or electrical contractors typically enter into supply and maintenance agreements with end-market consumers, which include commercial establishments, residential areas, and small businesses that use generators for emergency power backup. In addition, companies often appoint an in-house monitoring engineer to oversee the operation of numerous generators in industrial-scale settings. Stringent government regulations regarding reducing harmful carbon emissions are expected to boost the penetration of gas-based generators over diesel generators. This trend is anticipated to restrict the demand for diesel generators across all end-use sectors. However, low operating costs and low initial investment are among the key factors sustaining the current requirement for diesel generator sets. 


Key Companies profiled:


• AKSA Power Generation Company
• Atlas Copco AB
• Caterpillar
• Cummins Inc.
• Doosan Portable Power
• Generac Power System Inc.
• Honda India Power Products Ltd.
• Kohler Co.
• Rolls-Royce Plc
• Wartsila Corporation


Browse through Grand View Research's Category Power Generation & Storage Industry Research Reports.


• The global offshore pipeline market size was estimated at USD 13.97 billion in 2022 and is anticipated to expand at a compound annual growth rate (CAGR) of 4.2% from 2023 to 2030. The rising global demand for energy, particularly oil and natural gas, is poised to highlight the necessity for offshore pipelines, as they are vital in transporting such resources from offshore fields to onshore processing facilities, ensuring a stable supply of energy.


• The global battery recycling market size was estimated at USD 1.83 billion in 2023 and is expected to grow at a compound annual growth rate (CAGR) of 37.6% from 2024 to 2030. The industry is expected to grow rapidly during the forecast period owing to increasing popularity of electric vehicles (EVs) and renewable energy storage systems leading to a higher demand for batteries, and, in turn, driving the need for recycling.


Diesel Generator Market Segmentation


Grand View Research has segmented the global diesel generator market based on power rating, application, region:


Diesel Generator Power Rating Outlook (Revenue, USD Million, 2018 - 2030)


• Low Power Generator
• Medium Power Generator
• High Power Generator


Diesel Generator Application Outlook (Revenue, USD Million, 2018 - 2030)


• Industrial
• Commercial
• Residential


Diesel Generator Regional Outlook (Revenue, USD Million, 2018 - 2030)


• North America
o U.S.
o Canada
o Mexico
• Europe
o UK
o Germany
o Russia
o France
• Asia Pacific
o China
o Japan
o India
o South Korea
• Central & South America
o Brazil
o Argentina
• Middle East & Africa
o Saudi Arabia
o UAE


Order a free sample PDF of the Diesel Generator Market Intelligence Study, published by Grand View Research.


Key Diesel Generator Company Insights


Key companies are adopting several organic and inorganic expansion strategies, such as mergers & acquisitions, new product launches, capacity expansion, mergers & acquisitions, and joint ventures, to maintain and expand their market share.


• In May 2023, Cummins, a power generation equipment and engine manufacturer, launched a novel diesel generator set powered by their B45 engine, a 4.5-liter, four-cylinder diesel engine designed for power generation applications. This new generator set is expected to provide reliable power for a variety of industries, including construction, rental, and prime power


• In August 2022, Caterpillar launched three standby diesel generators ranging from 20 to 30 kilowatts (KW) for the North American market. These diesel generator sets, powered by the Cat C2.2 engine, are designed for small industrial, telecommunications, and commercial applications. They meet U.S. EPA emergency emission standards and industry safety certifications and offer features like exceptional performance, compact size, readily available parts, and optional enclosures

Tuesday, 27 August 2024

Hydrogen Generation Market To Forsee Commendable, Due To Growing Demand For Cleaner Fuel


Hydrogen Generation Industry Overview


The global hydrogen generation market size was estimated at USD 170.14 billion in 2023 and is expected to grow at a compound annual growth rate (CAGR) of 9.3% from 2024 to 2030. Demand for cleaner fuel and increasing government regulations for desulphurization of petroleum products. Hydrogen is an effective energy carrier, and this attribute is expected to contribute significantly to its further penetration into newer markets. Global electricity demand is anticipated to witness an increase of nearly two-thirds of current demand over the forecast period. Focus on projects related to distributed power & utility is anticipated to bolster industry’s growth.


Gather more insights about the market drivers, restrains and growth of the Hydrogen Generation Market


U.S. is among the early adopters of clean energy solutions in world for sectors such as power generation, manufacturing, and transportation. The U.S. Department of Energy (DOE) and Department of Transportation (DOT) introduced a Hydrogen Posture Plan in December 2006. This plan was aimed at enhancing research and development (R&D) and validating technologies that can be employed for setting up hydrogen infrastructure.


This plan provided deliverables set by the Federal government to support development of hydrogen infrastructure in the country. It was developed following the National Hydrogen Energy Vision and Roadmap. Development and construction of cost-effective and energy-saving hydrogen stations across the country are among key objectives planned by government agencies. All these factors are expected to propel hydrogen generation demand in the U.S.


German Ministry of Transport took an initiative in June 2012 to establish a countrywide hydrogen network and boost hydrogen infrastructure for hydrogen refueling stations. As a part of this initiative, the ministry signed a letter of intent (LoI) with industry players such as Total; The Linde Group; Air Products and Chemicals, Inc.; Daimler AG; and Air Liquide. Under its terms, these industry players were given a target to construct at least 50 hydrogen fueling stations by 2015 in metropolitan cities and major corridors in Germany.


Browse through Grand View Research's Sustainable Energy Industry Research Reports.


• The global voluntary carbon credit market size was estimated at USD 2.97 billion in 2023 and is projected to grow at a CAGR of 34.6% from 2024 to 2030. The market growth is driven by companies pledging to achieve net-zero emissions and the need for offsets to compensate for emissions that cannot be fully eliminated.


• The global energy storage as a service market size was valued at USD 1.2 billion in 2020 and is expected to expand at a compound annual growth rate (CAGR) of 10.7% from 2021 to 2028. The market is expected to be driven by the increasing demand for power management services and cost-effective battery backup power in case of a power outage.


Hydrogen Generation Market Segmentation


Hydrogen Generation Technology Outlook (Volume, Million Metric Tons; Revenue, USD Billion, 2018 - 2030)


• Steam Methane Reforming
• Coal Gasification
• Others


Hydrogen Generation Application Outlook (Volume, Million Metric Tons; Revenue, USD Billion, 2018 - 2030)


• Methanol production
• Ammonia Production
• Petroleum Refining
• Transportation
• Power Generation
• Others


Hydrogen Generation System Outlook (Volume, Million Metric Tons; Revenue, USD Billion, 2018 - 2030)


• Captive
• Merchant


Hydrogen Generation Source Outlook (Volume, Million Metric Tons; Revenue, USD Billion, 2018 - 2030)


• Natural Gas
• Coal
• Biomass
• Water


Hydrogen Generation Regional Outlook (Volume, Million Metric Tons; Revenue, USD Billion, 2018 - 2030)


• North America
o U.S.
o Canada
o Mexico
• Europe
o Germany
o Russia
o UK
o France
o Spain
o Italy
• Asia Pacific
o China
o India
o Japan
o South Korea
o Australia
• Central & South America
o Brazil
o Colombia
o Paraguay
• Middle East & Africa
o Saudi Arabia
o U.A.E
o South Africa
o Egypt


Order a free sample PDF of the Hydrogen Generation Market Intelligence Study, published by Grand View Research.


Key Companies profiled:


• Air Liquide International S.A
• Air Products and Chemicals, Inc
• Hydrogenics Corporation
• INOX Air Products Ltd.
• Iwatani Corporation
• Linde Plc
• Matheson Tri-Gas, Inc.
• Messer
• SOL Group
• Tokyo Gas Chemicals Co., Ltd.

Monday, 26 August 2024

Battery Recycling Market Will Help In Powering A Greener Tomorrow


Battery Recycling Industry Overview


The global battery recycling market size was estimated at USD 1.83 billion in 2023 and is expected to grow at a compound annual growth rate (CAGR) of 37.6% from 2024 to 2030. The industry is expected to grow rapidly during the forecast period owing to increasing popularity of electric vehicles (EVs) and renewable energy storage systems leading to a higher demand for batteries, and, in turn, driving the need for recycling. Governments globally are implementing regulations to promote the recycling of batteries and reduce environmental impact, which is expected to boost industry growth.


Gather more insights about the market drivers, restrains and growth of the Battery Recycling Market


The U.S. emerged as the largest market in North America in 2023. Increasing sales of EVs in the U.S. owing to the formulation of supportive federal policies, such as the Responsible Battery Recycling Act of 2022 California, and presence of leading industry players are expected to drive demand for batteries in the country over the forecast period. Responsible Battery Recycling Act of 2022 California instructs each battery retailer in the state to have a system for collection of used rechargeable batteries for recycling and reusing purposes.


The U.S. has emerged as a growing market for the recycling of li-ion batteries owing to the presence of large-scale li-ion recycling facilities in the country. For instance, Li-cycle Corp. inaugurated its new li-ion recycling facility with 120,000 square feet of warehousing space. This facility can process 10,000 tons of battery material for electric vehicles annually. The company possesses the capacity to recycle 60,000 electric vehicle batteries.


Browse through Grand View Research's Category Power Generation & Storage Industry Research Reports.


• The global subsea power grid systems market is expected to grow over the forecast period owing to increasing oil & gas exploration activities in major offshore locations. The regular electric power supply is essential to continue operations in such deep water locations. The depletion of on-shore oil & gas reserves has led to rising offshore reserves exploration, subsequently creating demand for subsea power grid systems.


• The global nuclear turbine generator market is expected to advance exponentially on account of rapid industrialization and increasing demand for energy to meet consumer and industrial needs. Rapid industrialization in emerging countries has provided a catalyst for energy needs across the globe. Fossil fuels are expected to remain the primary source of energy during the forecast period; however, they contribute largely to carbon dioxide emissions.


Battery Recycling Market Segmentation


Grand View Research has segmented the global battery recycling market based on chemistry, application, and region:


Battery Recycling Chemistry Outlook (Volume, Tons; Revenue, USD Million, 2018 - 2030)


• Lithium-ion
• Lead Acid
• Nickel
• Others


Battery Recycling Application Outlook (Volume, Tons; Revenue, USD Million, 2018 - 2030)


• Transportation
• Consumer Electronics
• Industrial


Battery Recycling Regional Outlook (Volume, Tons; Revenue, USD Million, 2018 - 2030)


• North America
o U.S.
o Canada
o Mexico
• Europe
o Germany
o U.K.
o France
o Italy
o Spain
o Poland
o Netherlands
• Asia Pacific
o China
o Japan
o South Korea
o Taiwan
o India
o Indonesia
o Malaysia
o Thailand
o Vietnam
o Australia
• Central & South America
o Brazil
o Argentina
o Chile
• Middle East & Africa
o UAE
o Saudi Arabia
o South Africa


Order a free sample PDF of the Battery Recycling Market Intelligence Study, published by Grand View Research.


Key Companies profiled:


• Call2Recycle
• Exide Technologies
• Gravita India Ltd.
• Glencore
• Cirba Solutions
• American Battery Technology Company
• Gopher Resource
• East Penn Manufacturing Co.
• Aqua Metals

Wednesday, 31 July 2024

Energy As a Service Market: A Comprehensive Analysis

 Energy As A Service Industry Overview

The global energy as a service market size was valued at USD 59.37 billion in 2020 and is expected to grow at a compound annual growth rate (CAGR) of 8.9% from 2021 to 2028. An increase in Distributed Energy Resources (DER), tax benefits for energy efficiency projects, new revenue generation streams for utilities, and a decrease in the cost of renewable power generation and storage solutions are some of the factors driving the growth. The market is driven by the rising potential of renewable energy, price volatility, and rising energy consumption are other significant factors driving growth. Organizations have gradually been looking for sustainable energy sources, which in turn is anticipated to positively influence the growth.

Gather more insights about the market drivers, restrains and growth of the Energy As A Service Market

The Energy as a Service (EaaS) concept is still at its nascent stage, especially in developing economies. The market for EaaS is segmented on the basis of service type and end user. The services include management of usage, supply, and assessment. Most energy providers are opting for partnerships and business collaborations in order to attract more consumers. Developed countries, such as the U.S. and Canada have laid down policies and regulatory standards to promote the adoption of EaaS.

Increasing focus on renewable as well as non-renewable energy sources that mainly support renewable energy due to lowers costs, reduced carbon footprint, environment-friendly, and energy-efficient is projected to contribute to the market growth. Increasing government investments in sponsoring renewable sources are anticipated to drive the growth of the market over the forecast period.

Energy as a service also provides the customers with the flexibility of choice regarding pricing and ownership. It also helps the operators customize energy generation projects based on different power requirements of the customers in terms of both robust and modern. The service also enables easy and rapid assimilation of energy storage assets with a distributed generation system.

Browse through Grand View Research's Power Generation & Storage Industry Research Reports.

• The global nickel zinc rechargeable battery market size was estimated at USD 13.60 million in 2023 and is projected to grow at a CAGR of 24.4% from 2024 to 2030. The rising demand for efficient and eco-friendly energy storage solutions, rapid expansion of electric vehicles, and ongoing advancements in battery technology are attributable factors for the market growth.

• The global military battery market size was estimated USD 1,403.50 million in 2023 and is expected to grow at a CAGR of 4.11% from 2024 to 2030. Technological advancements in battery chemistry and design significantly impact the military battery market. Developments in lithium-ion, solid-state, and other advanced battery technologies provide higher energy densities, longer life cycles, and improved safety features.

Energy As A Service Market Segmentation

Grand View Research has segmented the global energy as a service market report on the basis of service, end user, and region:

Energy As A Service Outlook (Revenue, USD Billion, 2016 - 2028)

• Supply
• Demand
• Energy Optimization

Energy As A Service End-user Outlook (Revenue, USD Billion, 2016 - 2028)

• Industrial
• Commercial

Energy As A Service Regional Outlook (Revenue, USD Billion, 2016 - 2028)

• North America
o The U.S.
o Canada
o Mexico
• Europe
o France
o Germany
o The U.K.
• Asia Pacific
o China
o India
o Japan
o South Korea
• Central & South America
o Brazil
• Middle East & Africa
o Saudi Arabia

Order a free sample PDF of the Energy As A Service Market Intelligence Study, published by Grand View Research.

Key Companies profiled:

• Schneider Electric
• Engie
• Siemens
• Honeywell International Inc.
• Veolia
• Enel X S.r.l.
• EDF

Wednesday, 10 January 2024

Bioplastics Industry Unveiling the Bioplastics Revolution For Cleaner Future

 Bioplastics Industry


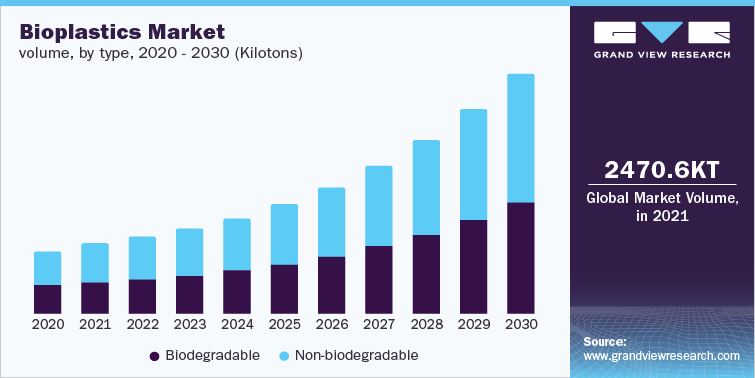
Global bioplastics sector data book, published by Grand View Research’s is a collection of market sizing information & forecasts, trade data, pricing intelligence, competitive benchmarking analyses, macro-environmental analyses, and regulatory & technological framework studies. Within the purview of the database, such information is systematically analyzed and provided in the form of outlook reports (1 detailed sectoral outlook report) and summary presentations on individual areas of research along with an agricultural statistics e-book.


The economic volume generated by the bioplastics industry was estimated at approximately 2,470.6 kilotons in 2021. This economic output is an amalgamation of businesses that are involved in the raw material suppliers, compounding of bioplastics & their additives, distribution & supply, and application of bioplastics.


Biodegradable Plastics Market Growth & Trends


The global biodegradable plastic market is expected to witness significant growth, particularly in emerging markets such as the United States, Canada and India. Increasing concerns about toxicity issues associated with petrochemicals and the depletion of crude oil reserves have spurred the development of bio-based polymers. Additionally, government regulations restricting the consumption of fossil-based plastics in certain applications such as food packaging and medical devices are expected to further stimulate the production of biodegradable plastics in the plastics industry.


Increasing concerns about the use of plastics have increased the demand for plastic alternatives in the market. With the pace of new product development and technological innovation, manufacturers in the industry are shifting their focus to developing biodegradable plastics. Innovative biopolymers such as PHAs (polyhydroxyalkanoates) and PLA (polylactic acid) are the key growth drivers of the biodegradable plastics market. These polymers are important members of the biopolymer family and are finally entering the market on a commercial scale. Due to their chemical composition, they possess a wide range of physical and mechanical properties required for various applications such as agriculture, medical devices and food packaging. 


Polylactic Acid Market Growth & Trends


The polylactic acid market is expected to witness growth on account of rising demand from end-use industries such as packaging, automotive & transport, electronics, textiles, and others. Packaging end-use segment dominated the PLA market in 2021 and accounted for a revenue demand from flexible packaging is fueling the growth of packaging industry globally. Increasing demand for packaged foods, snacks, ready to eat meal, and others are substantially propelling the growth of packaging industry. Thus, the growing packaging industry is further anticipated to create demand for polylactic acid during the forecast period. 


Manufacturers of polylactic acid aim to strengthen their market position by expanding their customer base. TotalEnergies Corbion, NatureWorks, LLC, COFCO International, Shanghai Tong-jie-liang Biomaterials Co., LTD., and others are leading producers of polylactic acid. Its good heat resistance and flexibility are used in various applications such as agriculture, packaging, textiles, automotive & transport, electronics, and others. These manufacturers focus on new product launches depending on the market requirements, technology innovations, and supply channels, as well as on mergers & acquisitions undertaken by their industry participants to meet the current and future demand for polylactic acid (PLA) in the growing packaging, textile, and other industries. 


Order your copy of Free Sample of “Bioplastics Industry Data Book - Biodegradable Plastic, Polylactic Acid (PLA), Bio-based Polyurethane (PU) and Biopharma Plastics Market Size, Share, Trends Analysis, And Segment Forecasts, 2022 - 2030, published by Grand View Research


Bio-based Polyurethane Market Growth & Trends


Companies operating in the global bio-based polyurethane market lay high emphasis on expanding their global footprints in an attempt to increase their revenue and market share. Companies are expanding their services in Asia Pacific to cater to the rising demand from developing countries. Countries such as India and China wherein the construction expenditure is growing significantly, are expected to provide new expansion opportunities for the market players over the forecast period.


Consumer goods end-use segment is expected to witness a growth rate of 6.5% during the forecast period. Bio-based polyurethane is widely used in the form of flexible polyurethane foam in various furniture applications such as furniture, beddings, sofas, and others owing to its properties such as softness, flexibility, and durability.  Electrical & electronics, packaging, and other end-use segments are expected to witness a growth rate of 6.0%, 7.0%, and 5.8%, respectively, over the forecast period.


Bio-based polyurethane foam is widely used in spray form for sealing holes, joints, cracks, and bonding other building materials, which ultimately reduces the amount of conditioning or heating required inside the building. Additionally, bio-based polyurethane is also used for structural elements, substrates, and other building components in construction industry. 


Biopharma Plastics Market Growth & Trends


The demand for protective wear is the next growing application segment after containers growing due to the COVID-19 outbreak put the global healthcare supply chain in the spotlight. This is mainly due to the improved healthcare sector in Europe, the Middle East, North America, and the Asia Pacific.


Additionally, according to the WHO, cancer is the second leading factor of death and accounts for 9.6 million deaths globally. Face, breast, and throat cancers are the commonly occurring cancers that require surgeries and chemotherapy. This has driven the protective wear market, which further is expected to increase the demand for biopharma plastics.


Syringe application segment is expected to have the highest penetration among all the segments in the global biopharma plastics market in 2021. Increasing utilization of plastics for manufacturing of syringes, as opposed to alloys and metals, has been a major factor contributing to the growth of the syringes application segment. Over the recent years, there has been a considerable rise in syringes production across the globe, which is majorly driven by the increasing demand from medical/healthcare and biopharma industry.


Go through the table of content of Bioplastics Industry Data Book to get a better understanding of the Coverage & Scope of the study.


Competitive Landscape


Key players operating in the Bioplastics Industry are –


• BASF SE
• Avantium
• NatureWorks LLC
• SABIC
• Total Corbion PLA
• Biome Technologies plc
• TEIJIN LIMITED 

Saturday, 18 November 2023

Solar PV Systems Industry: Harnessing The Sun's Power And Revolutionizing The Energy Landscape

 Solar PV Systems Industry


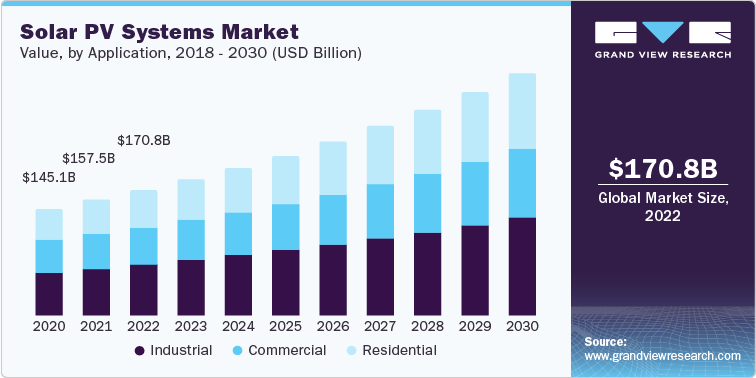
Global solar PV systems sector database is a collection of market sizing information & forecasts, trade data, pricing intelligence, competitive benchmarking analyses, macro-environmental analyses, and regulatory & technological framework studies. Within the purview of the database, such information is systematically analyzed and provided in the form of outlook reports (1 detailed sectoral outlook report) and summary presentations on individual areas of research along with a statistics e-book.


Access the Global Solar PV Systems Industry Data Book, 2023 to 2030, Compiled Report By Grand View Research


Solar PV Modules Market Report Highlights


The global solar PV modules market size is expected to reach USD 157.75 billion in 2022, expanding at a CAGR of 7.8% from 2023 to 2030, according to a new report by Grand View Research, Inc.
• The global solar PV modules market is expected to witness growth on account of rising environmental concerns regarding the increase in carbon emissions owing to the usage of conventional fuels for transportation and power generation purposes have prompted countries around the world to opt for cleaner and more efficient sources of power.
• Furthermore, under the Paris Climate Agreement, countries such as the U.S., Germany, India, Japan, and the UK have pledged to reduce their carbon footprints.
• Numerous governments across the world have framed various regulations to reduce greenhouse gas emissions.
• The Kyoto Protocol, which was introduced by the United Nations Framework Convention on Climate Change (UNFCCC) in 1997, was one of the first major steps toward controlling greenhouse gas emissions in various countries.
• It also led to increased investments in renewable energy generation methods such as wind, solar, and biogas. For instance, on January 9, 2023, Duke Energy Sustainable Solutions announced the expansion of its Green Source Advantage program with the option to supplement power usage with 100% renewable power with a new capacity of 4 GW.


Order your copy of Free Sample of “Solar PV Systems Industry Data Book –Market Size, Share, Trends Analysis And Segment Forecasts, 2023 - 2030” published by Grand View Research


PV Inverter Market Report Highlights


The global PV inverter market size is anticipated to reach USD 11.10 billion in 2022, registering a CAGR of 15.8% from 2023 to 2030, according to a new report by Grand View Research, Inc.


• Based on product, the string PV inverter dominated the market and accounted for the largest market share of 47.10% in 2023. This is due to its numerous advantages such as efficient energy conversion, grid integration, enhanced performance and monitoring, adaptability and scalability, and cost-effectiveness
• Based on end-use, the residential segment is expected to grow at the fastest CAGR of 20.4% over the forecast period. The increasing adoption of solar PV in the residential sector is driving the demand for PV inverters. According to the Solar Energy Industries Association (SEIA), annual solar PV installation in the residential sector in California, U.S., was recorded at 2,000 MW in 2022, up by over 40% compared to the previous year
• Asia Pacific dominated the market in 2023, owing to the increasing adoption of renewable energy in the residential, commercial and industrial sector. In addition, favorable government policies such as Pradhan Mantri Kisan Urja Suraksha Evam Uttham Mahabhiyan, Development of Solar Parks and Ultra Mega Solar Power Projects in India are further propelling the market growth
• The strengthening of market presence by major players is primarily driven by strategies such as mergers, acquisitions, and product launches. For instance, in March 2023, Semiconductor Components Industries, LLC collaborated with Sineng Electric Co., Ltd. to develop next-generation solar PV inverters to meet the growing demand for solar energy systems by end-users


Solar Charge Controller Market Report Highlights


The global solar charge controller market size is expected to reach USD 1.95 billion in 2022, expanding at a CAGR of 16.7% from 2023 to 2030, according to a new report by Grand View Research, Inc.
• By type, the Pulse Width Modulation (PWM) segment accounted for a significant market share in 2019 owing to PWM charge controller ability to self regulate to battery condition and provide constant voltage battery charging
• Maximum Power Point Tracking (MPPT) is anticipated to expand at the fastest CAGR over the forecast period. The growth can be attributed to the higher efficiency of MMPT technology and its ability to extract maximum power available from PV module under specified conditions
• The commercial application segment occupied the largest market share in 2019 and is expected to expand at the highest CAGR over the forecast period. Growing penetration of solar PV modules for power generation across commercial office spaces is expected to drive the solar charge controller demand across the segment
• Asia Pacific accounted for the largest revenue share in 2019, with China being the highest revenue contributor. Presence of major manufacturers, along with significant investments in the solar industry resulting in reduced production costs, is expected to boost the market growth in China.


Go through the table of content of Solar PV Systems Industry Data Book to get a better understanding of the Coverage & Scope of the study.


Competitive Landscape


The solar PV systems market players face strong competition from other regional and national players as well as from each other since they have a well-established supply chain network, knowledge of suppliers across markets, and well-informed about the power generation compliances and regulations for various end-use sectors. The market players compete based on product quality, production capacity, technology used to manufacture solar PV systems, and their geographical presence. Major players engage in investing in research and development, developing infrastructure, production facilities expansion, and mergers and acquisitions to vertically integrate their operations across the solar PV systems value chain. These initiatives help them expand their customer base, reduce production costs, develop state-of-the-art products and technologies, ensure competitiveness, and improve their revenue & operations profits.


Key players operating in the Solar PV Systems Industry are –


• JinkoSolar
• JA Solar
• Trina Solar
• LONGi Solar
• Canadian Solar
• SunPower Corporation
• First Solar
• Talesun
• Hanwha Group
• RISEN ENERGY Co. LTD.
• Yingli Solar
• GCL-SI
• HIANS Energy Solutions Ltd.
• Sunrun
• Trinity Solar, Inc